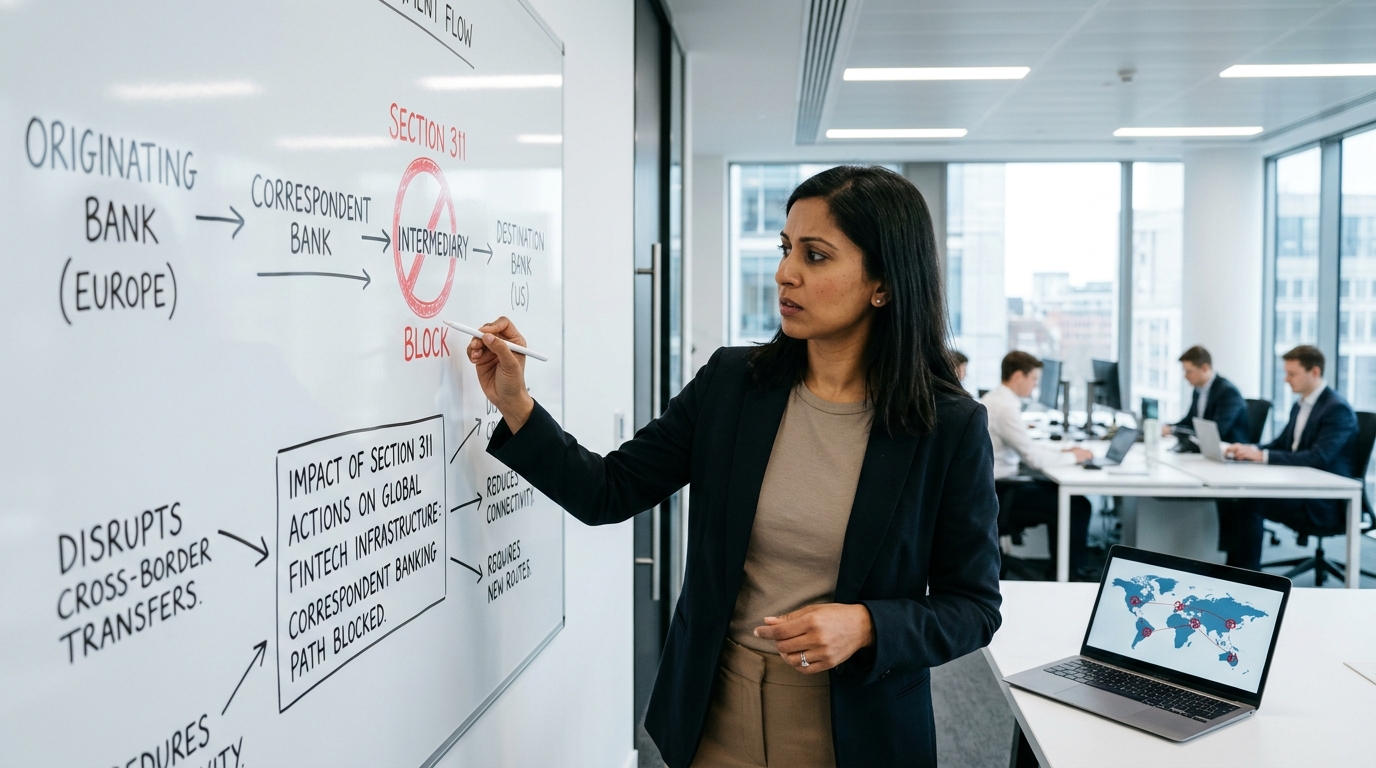
How Section 311 Actions Impact Cross-Border Transfers & Fintech Infrastructure
The Nuclear Option in Global Finance: How FinCEN’s Section 311 Actions Shatter Correspondent Banking, Dollar Settlement, and Fintech Rails
In international finance, there is no single regulatory enforcement tool quite as devastating as Section 311 of the USA PATRIOT Act.
When the U.S. Department of the Treasury’s Financial Crimes Enforcement Network (FinCEN) invokes a Section 311 action, it doesn't just issue a fine or initiate a protracted civil suit. It effectively wields the sovereign power of the U.S. dollar to server an entire institution—or even an entire foreign jurisdiction—from the global financial system.
For regional banks, cross-border payment processors, and modern fintech platforms, a Section 311 action isn't a distant regulatory headache. It is an immediate structural crisis. When FinCEN isolates a foreign target by prohibiting U.S. correspondent banking access, the shockwaves instantly disrupt cross-border wires, sever clearing rails, freeze liquidity, and cascade into non-bank fintech infrastructure.
Below is an in-depth operational analysis of what actually happens across global payment networks when FinCEN presses the Section 311 button—and how the modern cross-border ecosystem moves to survive it.
1. Mechanics of the Target: What is a Section 311 Action?
Under Section 311 of the USA PATRIOT Act (31 U.S.C. 5318A), the Secretary of the Treasury is empowered to designate a foreign financial institution, a class of transactions, a type of account, or a whole geographic jurisdiction as being of "Primary Money Laundering Concern."
Once FinCEN makes this determination, it can impose one or more of five graduated Special Measures:
- Recordkeeping and Reporting: Requiring U.S. institutions to maintain detailed records and submit reports on specific transactions.
- Beneficial Ownership Information: Demanding identification of the beneficial owners behind specific accounts.
- Payable-Through Account Information: Mandating disclosures regarding individuals permitted to use payable-through accounts.
- Correspondent Account Information: Requiring data on entities accessing foreign correspondent accounts.
- Prohibition or Conditions on Correspondent Accounts (The "Nuclear Option"): Explicitly barring U.S. financial institutions from opening, maintaining, or processing transactions through any correspondent or payable-through account for—or on behalf of—the target entity.
When FinCEN invokes Special Measure 5, the enforcement action completely isolates the target from the U.S. financial clearing system. Because international U.S. dollar settlements (processed through Fedwire and CHIPS) rely on correspondent accounts hosted by U.S. banks, a targeted institution instantly loses its ability to handle USD transactions globally.
FinCEN Proposes Rule Revoking Banque Misr UAE’s U.S. Correspondent Banking Access Over Iranian Sanctions Violations
2. The Chain Reaction on Dollar Settlement and Wire Infrastructure
When a Section 311 designation takes effect, the immediate consequences unfold rapidly across global money movement systems.
Immediate Isolation of Nostro and Vostro Networks
Domestic and international banks communicate through networks of Nostro accounts ("our money held at your bank") and Vostro accounts ("your money held at our bank"). Foreign banks rely on Vostro accounts held at U.S. Money Center Banks (such as JPMorgan Chase, Citibank, or Bank of New York Mellon) to process transactions denominated in U.S. dollars.
Under Special Measure 5, U.S. clearing banks are legally obligated to close all Vostro accounts belonging to the target institution. U.S. banks are also required to take reasonable steps to ensure their correspondent accounts are not used indirectly to clear transactions for the targeted firm.
This indirect access prohibition creates a powerful ripple effect: foreign intermediary banks that maintain relations with the targeted bank must instantly sever their own connections with that entity, lest they risk losing their own access to U.S. dollar clearing rails.
Frozen Wires "Mid-Flight"
Because Section 311 enforcement requires U.S. financial institutions to conduct rigorous due diligence, any SWIFT transaction containing routing instructions, BIC codes, or reference text tied to the designated target will be flagged by automated sanction screening tools.
- Transaction Interception: Payments in transit are routed to specialized internal compliance units at U.S. intermediary banks.
- Account Freezes & Rejections: Wires caught mid-flight are restricted or blocked from settling.
- Liquidity Black Holes: Millions of dollars in commercial cross-border transactions—often belonging to innocent end-users or businesses utilizing the target bank purely for transit—become trapped in administrative holding accounts pending federal clearance.
Accelerated Regional "De-risking"
Beyond the direct target, Section 311 actions trigger widespread risk-aversion (known as "de-risking") across the banking sector.
Major international banks frequently respond by systematically cutting off foreign correspondent relationships across entire high-risk regions to avoid potential compliance liabilities. Smaller regional financial institutions in developing markets are often offboarded entirely, severely limiting their access to direct USD clearing services.
3. The Crossfire Impact on Fintech Infrastructure and Non-Bank PSPs
Modern fintech platforms, cross-border payment processors (PSPs), and digital wallet providers rarely operate as independent banks. Instead, they rely on Banking-as-a-Service (BaaS) frameworks, leveraging institutional banking partners to maintain settlement rails and hold underlying foreign exchange (FX) reserves.
When a regional banking partner is struck by a Section 311 action, the impact propagates quickly across dependent fintech ecosystems:
Virtual Account Invalidation
Many cross-border fintech platforms issue Virtual Account Numbers (VANs) to merchants, freelancers, and importers. If the underlying bank issuing those account details is caught in a Section 311 action, those virtual routing details become useless overnight. Inbound transfers bounce, vendor payouts fail, and merchants find themselves temporarily cut off from their primary operating capital.
Settlement Engine Halts
Cross-border payment companies often maintain pool accounts at regional banks to facilitate foreign currency exchanges and local market payouts. When a financial institution loses access to U.S. dollar correspondent accounts, these liquidity pools are essentially frozen.
Fintechs are forced to scramble to find alternative clearing partners—a process that normally requires months of legal due diligence and technical onboarding—all while facing operational suspensions and reputational damage.
Collateral System Collapses
Fintech startups that rely on a single banking partner face immediate platform vulnerabilities. If a company's sole banking pipeline is disabled by a regulatory action, the platform cannot process transactions, leaving end-users unable to withdraw funds, pay international suppliers, or convert currencies.
4. Analytical Breakdown: Fact vs. Speculative Horizon
To understand how market participants adapt to these regulatory measures, it is essential to distinguish between verified regulatory realities and evolving market trends.
| Dimension | Verified Realities (Factual Record) | Future Scenarios & Market Sentiment (Speculative) |
| Regulatory Enforcement | FinCEN can unilaterally isolate institutions from USD correspondent networks using Special Measure 5. | Regulatory frameworks may increasingly incorporate automated, AI-driven compliance flags to instantly trace nested secondary transactions in real time. |
| Correspondent Impact | U.S. intermediary banks systematically sever Nostro/Vostro ties with designated target banks. | Smaller regional markets could face heightened risk of financial isolation, potentially accelerating the search for alternative settlement currencies. |
| Fintech Dependency | Non-bank financial platforms relying on targeted institutions experience operational outages and liquidity freezes. | Fintech platforms may transition toward multi-homed, redundant banking architectures to automatically re-route settlement pipelines if an intermediary fails. |
| Alternative Settlement | Section 311 enforcement relies on the U.S. dollar's role as the dominant currency for global trade. | Prolonged regulatory pressures could encourage the development of non-USD clearing networks, regional payment integration schemes, or stablecoin rails. |
5. Strategic Horizon: Potential Market Outcomes and Adaptive Models
As regulatory scrutiny intensifies, market participants, regional institutions, and fintech companies are evaluating various long-term strategies to maintain operational resiliency.
Scenario 1: Transitioning to Multi-Homed Fintech Architectures
To avoid single points of failure, modern fintech platforms are moving away from single-bank dependencies. Market participants are increasingly adopting multi-homed infrastructure, maintaining relationships with multiple licensed banking partners across different legal jurisdictions.
By utilizing dynamic, smart routing APIs, cross-border payment platforms can theoretically re-route pending transactions away from a disrupted banking partner within minutes, preserving operational continuity.
Scenario 2: Rise of Regional Clearing Mechanisms and Bilateral Networks
Repeated Section 311 enforcement actions and broader de-risking trends have encouraged regional economies to explore alternative clearing mechanisms.
Initiatives such as the Pan-African Payment and Settlement System (PAPSS) and various multi-central bank digital currency (mBridge) projects represent structural efforts to allow nations to trade using local currencies, reducing their overall exposure to foreign correspondent banking channels.
Scenario 3: Decentralized and Tokenized Dollar Alternatives
Some market analysts suggest that persistent correspondent banking disruptions could accelerate the adoption of asset-backed digital currencies and stablecoins (such as USDC or USDT) for cross-border commercial trade.
Because fiat-backed stablecoins run on distributed public networks, they allow counterparties to move dollar-equivalent value peer-to-peer without relying on traditional correspondent banking pipelines. However, because major stablecoin issuers remain subject to U.S. regulatory oversight, these digital assets are also developing their own compliance frameworks and blacklisting procedures.
6. Executive Takeaway: Building Resilient Global Payment Infrastructure
FinCEN's Section 311 authority highlights a key structural reality of global finance: access to U.S. dollar clearing is a privilege governed by strict regulatory standards, not an automatic guarantee.
When a Section 311 designation is issued, the resulting isolation of correspondent accounts demonstrates how quickly regulatory actions can impact global money movement. For regional banks, institutional payment providers, and digital fintechs, surviving in this environment requires proactive operational design:
- Eliminate Single Points of Failure: Diversify clearing paths across multiple institutional banking partners.
- Maintain Real-Time Transparency: Implement strict Transaction Monitoring Systems (TMS) to detect high-risk indirect flows before regulatory intervention occurs.
- Prioritize Operational Flexibility: Build modular payment architectures capable of updating underlying settlement routes if a primary correspondent partner is restricted.
In an interconnected global economy, long-term operational success depends on building payment infrastructure that is robust, compliant, and structurally resilient against regulatory shocks.