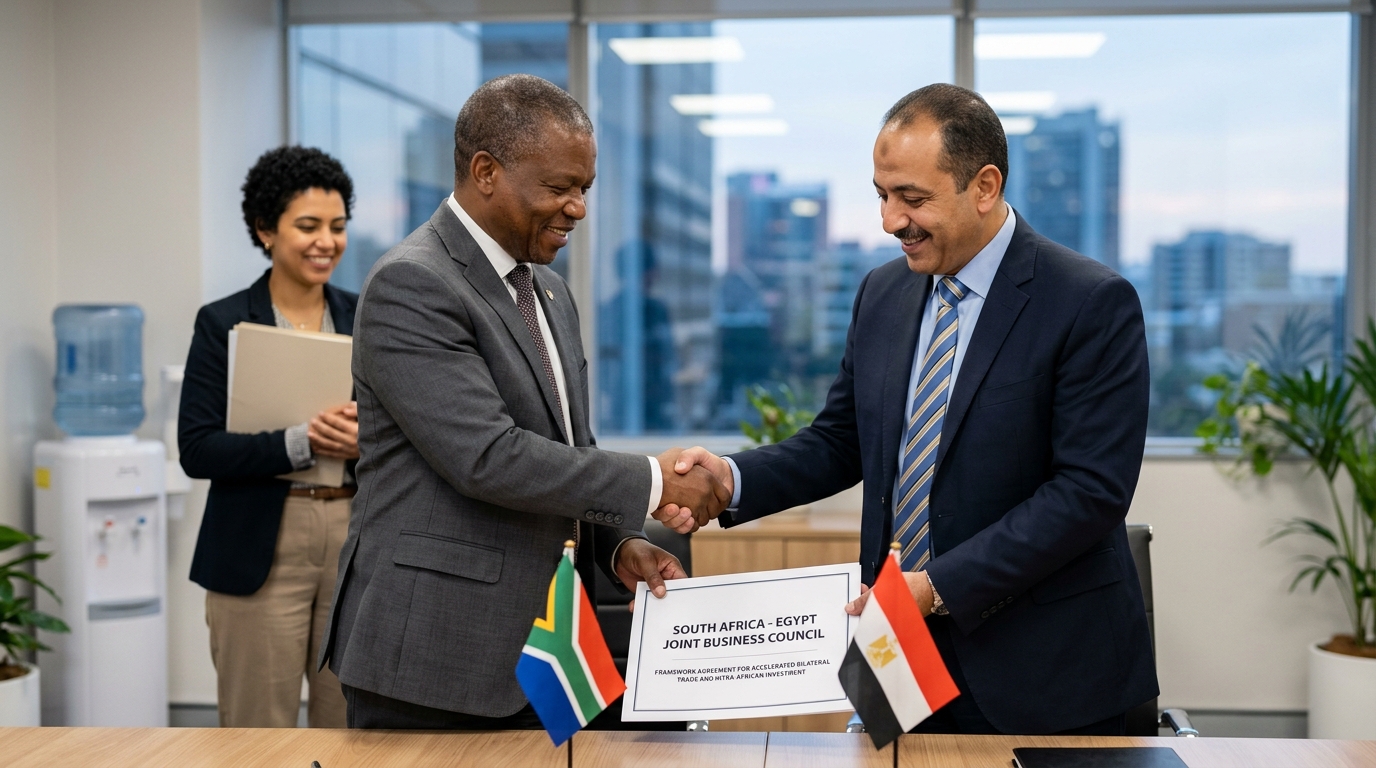
South Africa and Egypt Form Joint Business Council to Accelerate Bilateral Trade and Intra-African Investment Frameworks
Structural Shift or Temporary Calm? What Global Growth Stabilization Really Means for the World Economy
The global economy is attempting a high-wire balance, where fragile diplomatic breakthroughs in the Middle East and steadying macroeconomic metrics are offering the world a rare moment of structural breathing room.
For over two years, executive suites, institutional investors, and central bankers have operated in a posture of continuous crisis management. Pervasive inflation, aggressive monetary tightening, and persistent geopolitical friction along critical maritime trade corridors created a multi-front economic shock.
Yet, recent consensus reports from top economic institutions and chief economists indicate a distinct shift: global growth is showing concrete signs of stabilization. Crucially, this recalibration is occurring alongside nascent diplomatic steps in the Middle East—a development that has helped ease immediate disruptions across global supply chains and energy markets.
However, beneath the headline stabilization lies a complex web of structural shifts, lingering supply chain realignments, and forward-looking economic possibilities. Understanding this landscape requires looking beyond surface-level metrics to analyze where the global economy stands today—and where it could head next.
Factoring In the Global Economic Calibration
To understand the scope of the current economic picture, it is essential to separate verified, structural data from sentiment-driven market movements. Global output has not returned to the rapid expansion eras of past decades; rather, it has entered a phase of lower, but significantly less volatile, equilibrium.
1. Macroeconomic Baseline and Inflation Dynamics
Over the past 24 months, central banks globally—including the U.S. Federal Reserve, the European Central Bank (ECB), and the Bank of England—executed one of the most synchronized policy tightening cycles in modern history. The explicit goal was to curb post-pandemic demand spikes and neutralize supply-side inflationary pressure.
Recent economic indicators suggest that these policy measures have largely achieved their baseline objective:
- Inflation Cooldown: Headline consumer price indices across major developed economies have retreated significantly from their peak levels, moving closer to institutional target bands.
- Resilient Labor Markets: Despite elevated borrowing costs, labor markets across key industrial economies have avoided widespread contraction, sustaining baseline consumer demand.
- Growth Convergence: Emerging markets and developed economies are showing signs of growth convergence, reducing the stark performance divergence seen throughout 2022 and 2023.
2. Supply Chains and Strategic Maritime Corridors
Global supply chains served as the primary transmission mechanism for inflation throughout recent shocks. Disruption in major maritime passageways—such as the Red Sea, Suez Canal, and Panama Canal—forced global shipping lanes to reroute, driving up freight costs, transit times, and operational insurance premiums.
Recent diplomatic efforts in the Middle East have provided much-needed operational predictability:
- Freight and Transit Normalization: As diplomatic channels have reduced immediate security risks across vital shipping channels, ocean freight rates have retreated from peak panic pricing, easing cost pressures for global importers and exporters.
- Inventory Realignment: Corporations that shifted from "Just-in-Time" to "Just-in-Case" inventory management are beginning to optimize inventory levels, balancing supply chain resilience with reduced capital tie-ups.
- Energy Flow Regularity: Stability across major transit zones has reduced energy transportation premiums, ensuring a steadier flow of crude oil and liquefied natural gas (LNG) to energy-dependent industrial hubs across Europe and Asia.
| Economic Vector | Crisis Peak Conditions | Current Stabilized Baseline | Key Structural Driver |
| Global Shipping Costs | Extreme spikes due to rerouting | Moderating toward historical averages | Easing maritime tension & normalized routes |
| Monetary Stance | Aggressive, synchronized rate hikes | Pause phase / Selective recalibration | Moderating inflation figures |
| Energy Commodity Volatility | High risk premiums on oil/gas | Narrowing price bands | Diplomatic progress & steady production |
| Supply Chain Posture | Defensive stockpiling ("Just-in-Case") | Balanced inventory management | Operational route predictability |
The Horizon: Three Forward-Looking Scenarios for the Global Economy
While verified data confirms a period of macroeconomic stabilization, the future trajectory of the global economy remains dependent on multiple intersecting variables. Analyzing forward-looking scenarios allows decision-makers to evaluate possibilities without treating speculative outcomes as guarantees.
Scenario A: The Soft Landing and Productivity Renewal (Optimistic Probability)
In this scenario, current diplomatic progress holds, establishing long-term regional stability and allowing international trade corridors to operate without disruption.
- Monetary Recalibration: Central banks, confident that inflation is durably anchored near target rates, initiate measured rate cuts. This reduces capital costs and unlocks delayed enterprise investments in machinery, real estate, and digital infrastructure.
- Technology-Driven Productivity: Capital reallocation toward emerging technologies—such as artificial intelligence, industrial automation, and advanced clean-energy grids—yields tangible total factor productivity (TFP) gains across manufacturing and services.
- Global Trade Expansion: Normalized supply chains and steady consumer spending drive a renewed expansion in cross-border trade, particularly across emerging manufacturing hubs in Southeast Asia, Latin America, and Eastern Europe.
Scenario B: Fragmented Growth and Structural Trade Blocs (Baseline Probability)
Under this middle-path scenario, global growth remains positive but continues to operate within a structurally altered, more regionalized framework.
- Nearshoring and Friendshoring: Rather than returning to fully frictionless global trade, corporations continue diversifying supply networks to mitigate geopolitical risk. Strategic industries—such as semiconductors, pharmaceuticals, and critical minerals—remain anchored within aligned trading blocs.
- Targeted Industrial Policies: National governments maintain active subsidies and domestic manufacturing mandates, leading to localized capital investments but slightly higher overall production costs for international commerce.
- Divergent Central Bank Paths: Major central banks move asynchronously. Some cut rates to boost sluggish domestic growth, while others hold rates higher for longer to manage persistent localized wage growth or energy import costs.
Scenario C: Supply Shocks and Volatility Recurrence (Risk Probability)
This scenario considers the potential impact if diplomatic progress falters or new economic headwinds emerge unexpectedly.
- Re-emerging Logistics Friction: A resumption of maritime corridor disruptions forces global shipping lines back onto longer, costlier trade routes, driving up transit times and reigniting transport-driven inflation.
- Energy Market Spikes: Supply restrictions or renewed regional instability cause sudden upward spikes in energy prices, squeezing margins for industrial producers and dampening consumer sentiment.
- Monetary Policy Reversals: Persistent inflation forces central banks to halt planned rate cuts or re-engage in rate increases, tightening monetary conditions and raising debt-service burdens for both sovereign states and private enterprises.
Key Variables to Track Next
The current alignment of chief economist indicators and diplomatic progress points to an immediate period of economic stabilization. However, transitioning from temporary calm to sustained global expansion depends on several structural developments.
To evaluate whether this stabilization marks a durable trend or a brief interlude, market participants and analysts will be watching four critical indicators:
- Maritime Transit Volume Trends: Sustained normalization of commercial vessel traffic through major global choke points will signal genuine operational stabilization in physical trade networks.
- Central Bank Policy Symmetry: The degree to which major monetary authorities align their rate pathways will indicate whether global inflation pressures are cooling uniformly or fragmenting by region.
- Enterprise Capital Expenditure Statements: Quarterly corporate filings across major industrial sectors will reveal whether business leaders are shifting capital allocation from defensive risk mitigation toward long-term productivity and expansion.
- Energy Commodity Inventory Buffers: National strategic reserve levels and corporate inventory buffers will show how effectively major economies are insulated against potential future supply shocks.
As the global economy navigates this transitional phase, the interaction between geopolitical diplomacy, policy recalibration, and corporate adaptability will determine the shape of international growth in the years ahead.
Disclaimers & Operational Notes
- Informational Purpose Only: This article is prepared strictly for analytical, educational, and editorial purposes. It does not constitute financial, legal, investment, or strategic planning advice.
- Forward-Looking Statements: References to prospective market scenarios, economic trends, or potential future outcomes represent speculative analysis based on prevailing market sentiment and standard economic modeling, not factual predictions or guaranteed results.
- Data Verification: All historical macroeconomic figures and institutional references reflect verified public datasets available as of the date of publication.