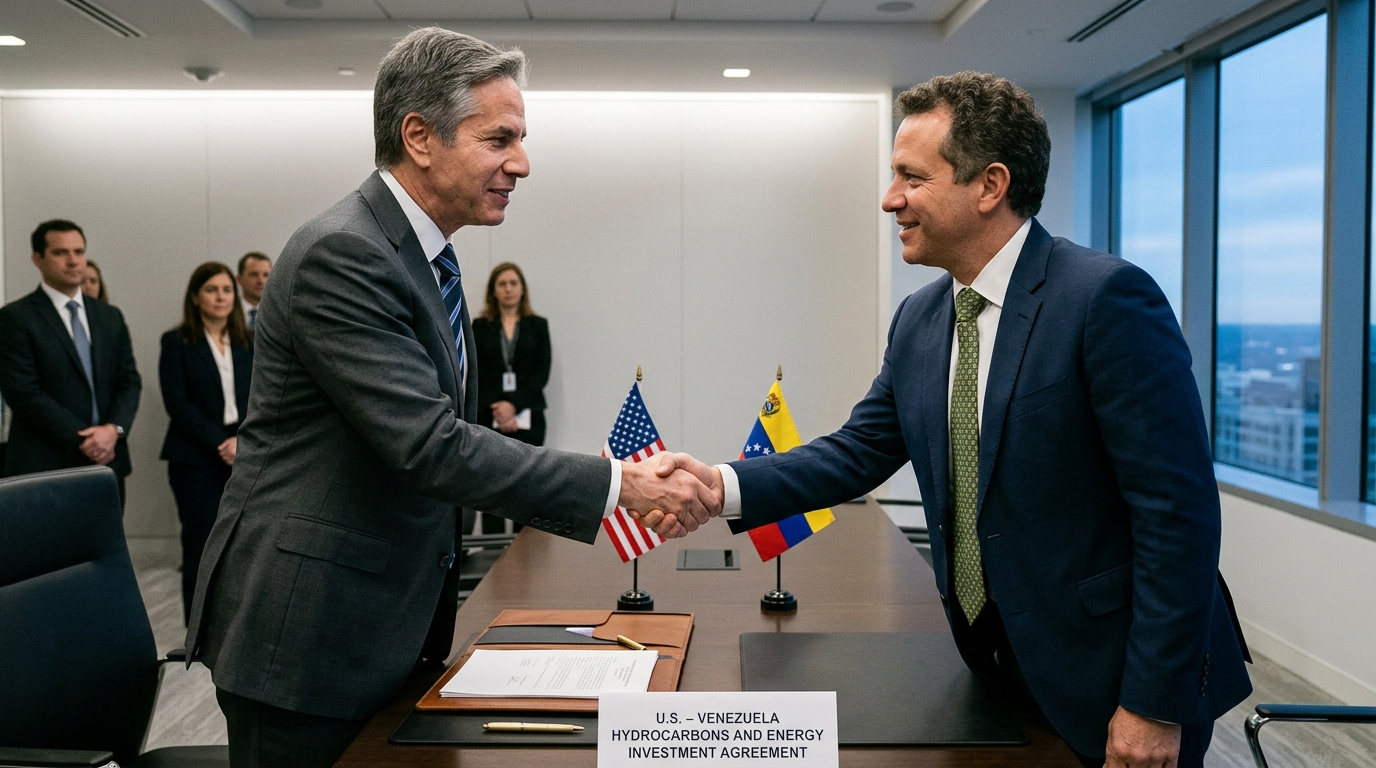
U.S. and Venezuela Reach Historic Bilateral Hydrocarbons Infrastructure and Energy Investment Agreement
Redrawing the Global Energy Map: Inside the Historic U.S.–Venezuela Bilateral Hydrocarbons Accord
In a landmark shift that redefines Western Hemisphere energy dynamics, the United States and Venezuela have entered into what is being framed as the largest energy investment accord in modern history.
Following months of intense geopolitical realignment and restructuring in Caracas, Washington officialdom and Venezuelan interim leadership announced a broad framework to open 65 billion barrels of proven crude reserves to major private capital inflows and joint operational control.
With promised capital deployment exceeding $100 billion, the agreement aims to overhaul rusted infrastructure across Lake Maracaibo and the Orinoco Heavy Oil Belt.
Coming against the backdrop of persistent energy market volatility and maritime friction in key global chokepoints like the Strait of Hormuz, this accord is more than an oil deal: it is a high-stakes attempt to pivot the core of Western energy security back to the Americas.
Can an influx of private capital and technical expertise rebuild a neglected energy grid and stabilize international supply lines, or will complex regulatory, constitutional, and execution hurdles challenge this ambitious pact?
To understand the scope of the bilateral agreement, it is essential to examine the verified operational metrics, legal mechanisms, and economic parameters surrounding the accord.
The Structural Framework of the Accord
The agreement establishes a framework for direct private-sector management, infrastructure rehabilitation, and long-term extraction rights across major Venezuelan hydrocarbon basins.
- Targeted Asset Footprint: The bilateral initiative covers 17 strategic oilfields containing an estimated 65 billion barrels of proven reserves. These assets encompass both mature light-crude fields in the Lake Maracaibo region and massive extra-heavy crude assets within the Orinoco Belt. AzerNews+ 1
- Capital Mobilization & Tax Revenue Projections: According to official statements from Caracas and Washington, the accord aims to mobilize upwards of $100 billion in private energy investment over its lifecycle. The Venezuelan interim administration projects the multi-year development could generate over $209 billion in state tax revenues and royalties.
- Regulatory & Concession Mechanics: The arrangement is structured around long-term joint venture and concession-style operating models. Private operators and joint management structures will oversee daily extraction, pipeline transport, and refinery blending operations, supported by recent partial reforms to Venezuela's Hydrocarbons Law designed to broaden foreign equity participation. Venezuela Analysis+ 1
- Strategic Petroleum Reserve Off-Take: A key provision of the bilateral alignment includes direct off-take agreements to supply heavy crude to Gulf Coast refiners and assist in replenishing the U.S. Strategic Petroleum Reserve (SPR).
Infrastructure Challenges on the Ground
While the financial figures are massive, the physical reality of Venezuela's energy grid presents immediate operational bottlenecks:
- Midstream Degradation: Years of underinvestment have left pipelines, pumping stations, and upgraders requiring extensive structural rehabilitation before output can scale significantly.
- Power Grid Instability: Reliable extraction in the Orinoco Belt requires consistent electrical supply. Investment capital must be allocated not only to oil wells, but to regional thermal and hydroelectric generation.
- Upgrader Capacity: Extra-heavy Orinoco crude requires specialized blending with lighter diluents or processing through regional upgrading facilities before export, making supply-chain logistics a primary capital priority.
Comparative Breakdown: Energy Portfolio Realignment
| Metric / Dimension | Pre-Agreement Status (Prior Years) | Post-Agreement Framework Target |
| Primary Operational Operators | State-dominated PDVSA with limited joint ventures | Expanded private joint ventures & international consortiums |
| Capital Source | Restricted state budget & bilateral credit lines | $100B+ international private capital mobilization |
| Primary Export Destinations | Highly fragmented, subject to trade sanctions & discounts | Direct Gulf Coast refining integration & SPR off-take |
| Regulatory Framework | Strict state-monopoly hydrocarbon laws | Reformed Hydrocarbons Law permitting concession-style models |
As international energy majors, logistics providers, and macro analysts digest the scale of the agreement, several forward-looking scenarios are taking shape.
Note: The following scenarios represent market sentiment, structural economic modeling, and industry analysis rather than guaranteed market outcomes.
Scenario A: The Western Hemisphere Pivot (Estimated Probability: ~45%)
- The Hypothesis: Private capital deployment proceeds rapidly, with oilfield service providers restoring key midstream pipelines and upgrading infrastructure over a 24-to-36-month window. Venezuelan production ramps steadily past 2 million barrels per day, providing heavy crude directly to U.S. Gulf Coast refineries optimized for heavy slops.
- Market Sentiment Impact: Global oil markets price in a structural "buffer" of Atlantic Basin supply, dampening price spikes caused by Middle Eastern transit disruptions and stabilizing global shipping costs.
Scenario B: The Friction-Bound Plateau (Estimated Probability: ~40%)
- The Hypothesis: Logistics and capital deployment encounter practical delays. While initial fields return to service quickly, broader infrastructure decay requires far more capital and time than originally budgeted. Daily output increases moderately (by 300,000 to 500,000 barrels per day) but hits midstream capacity bottlenecks.
- Market Sentiment Impact: Energy prices remain range-bound. Investors adopt a selective approach, prioritizing immediate low-hanging light-crude rehabilitations over complex, capital-intensive extra-heavy oil upgraders.
Scenario C: The Regulatory Bottleneck (Estimated Probability: ~15%)
- The Hypothesis: Domestic political pushback or complex legal challenges surrounding constitutional resource provisions delay contract finalizations. International investors pause major capital disbursements pending long-term statutory clarifications.
- Market Sentiment Impact: Capital flows slow down, forcing project operators to rely on smaller, incremental risk-managed phases rather than transformative multi-billion-dollar buildouts.
The U.S.–Venezuela bilateral energy agreement marks a fundamental realignment of global hydrocarbon logistics. By pairing the world's largest proven oil reserves with Western private capital and refining capacity, the initiative attempts to construct a resilient, hemisphere-bound energy supply chain capable of insulating markets from distant geopolitical shocks.
For macro strategists, energy market participants, and policy analysts, three critical variables will determine how quickly this agreement transitions from paper to physical reality:
- Midstream Execution Timelines: Track the speed at which service companies reactivate idle drilling rigs, repair export terminals, and stabilize regional power delivery.
- Private Capital Inflows: Monitor early-stage equity commitments and credit facility announcements from private energy consortia.
- Refinery Integration & Off-Take Volumes: Observe volume trends for heavy-crude shipments arriving at U.S. Gulf Coast facilities and official SPR replenishment logs.
The headlines have established the high-stakes narrative; the true test now lies in the physical execution across the oilfields of Maracaibo and the Orinoco Belt.