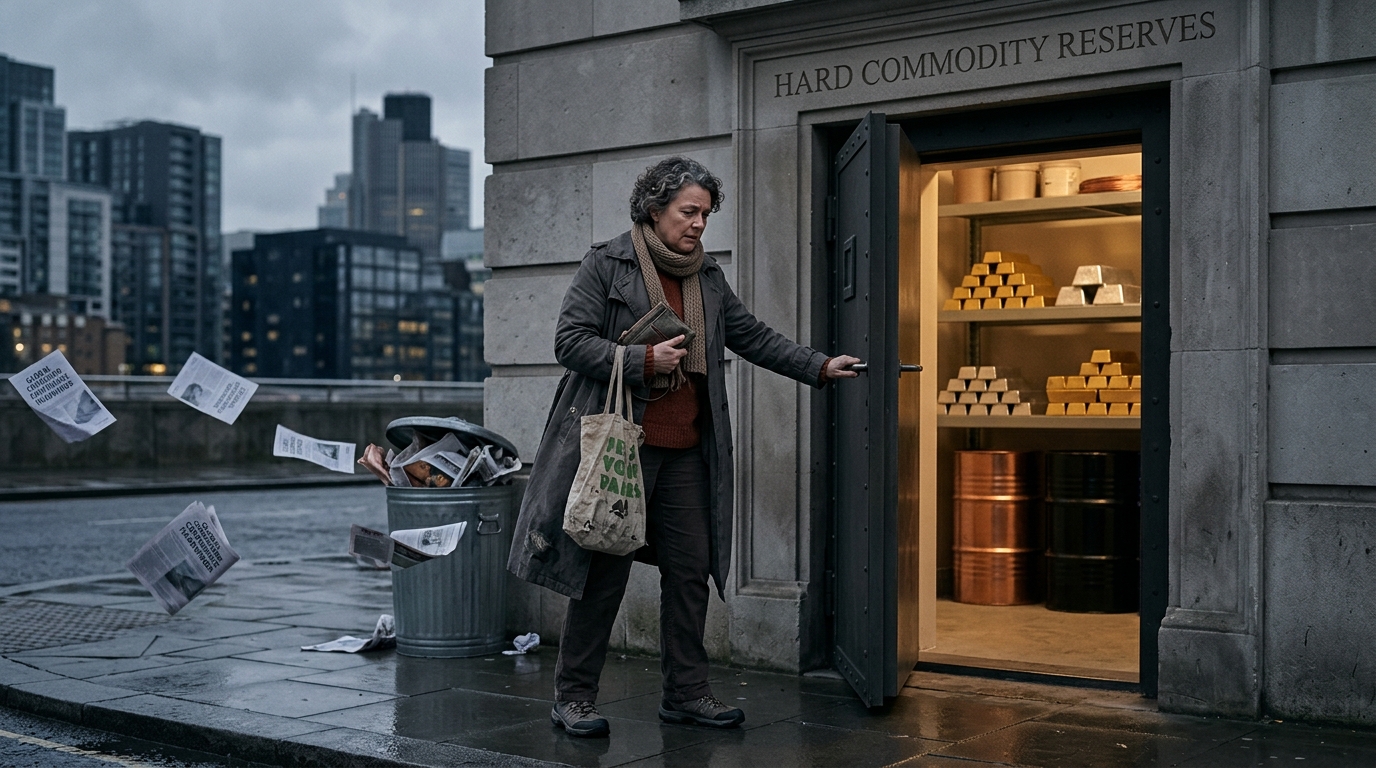
Why Global Consumer Confidence Headwinds Are Triggering a Strategic Shift Toward Hard Commodity Reserves
The psychological anchor of the global consumer is starting to slip, and sovereign balance sheets are quietly preparing for the fallout.
While main street shoppers tighten their belts, trim discretionary budgets, and battle persistent real-wage fatigue, sovereign institutions and mega-corporations are executing a massive structural shift behind the scenes. They are no longer placing all their chips on debt instruments or fiat liquidity buffers. Instead, a silent pivot is underway—one that moves institutional capital away from soft consumer demand metrics and directly into hard commodity reserves, physical assets, and sovereign collateral.
Is this strategic pivot a temporary hedge against persistent inflation, or are institutional actors preparing for a fundamental realignment of the global monetary apparatus?
"When main street stops buying, sovereigns start hoarding. The global consumer hasn’t just paused—they are forcing a systemic pivot where physical reserves, strategic metals, and hard energy assets replace debt as the ultimate stores of value."
The signs are accumulating across major economic indicators. Global consumer sentiment metrics face ongoing headwinds, weighed down by elevated interest rates, persistent price levels, and tightening personal financial margins.
Yet, rather than waiting for consumer-led growth to reignite the economic engine, macro strategists, sovereign wealth funds, and central banks are executing a textbook asset rotation. By funneling capital into strategic physical commodity reserves—ranging from industrial metals and critical energy stocks to official bullion holdings—institutional players are signaling a profound shift in risk management. The core narrative is changing: liquidity is no longer just paper cash on a balance sheet; it is tangible, physical ownership of essential resources.
To understand why capital is flowing into hard commodity reserves, one must look closely at the data defining consumer confidence headwinds and sovereign allocation trends.
1. The Anatomy of Consumer Headwinds
Data across global markets illustrates an enduring squeeze on household balance sheets:
- Sentiment Pressure: The Ipsos Global Consumer Confidence Index reflected a drop in late 2026 to 48.4, driven by notable declines in investment and current economic climate sub-indices.
- Discretionary Slowdown: High living costs continue to erode purchasing power, causing households to prioritize essential goods while cutting discretionary spend.
- Debt Servicing Costs: Extended periods of elevated borrowing costs have increased credit card and mortgage servicing loads, curbing credit-fueled consumer spending.
2. Sovereign & Institutional Commodity Off-Take
Rather than leaving cash idle or strictly in yield-bearing paper debt, sovereign entities are building tangible buffers:
- Central Bank Metal Accumulation: Net central bank purchases of physical gold reached a record 288.9 tonnes in Q2 2026 alone—a 62% year-over-year surge—driven by nations seeking sanction-resistant reserve assets with zero counterparty risk.
- European Reserve Realignment: According to European Central Bank data, gold’s share of total official foreign reserves reached 27% by the end of 2025 (driven by both net buying and valuation reallocations), outpacing paper reserves like US Treasuries.
- Private-Sector Reserve Drivers: Major corporate treasury operations and private institutions are joining the rush; notably, stablecoin issuer Tether acquired over 100 tonnes of physical gold in a single year, outstripping individual purchases made by many sovereign nations. GoldSilver
| Economic Variable | Traditional Consumer Expansion Phase | Hard Reserve Strategic Pivot |
| Primary Growth Driver | Household consumption & debt expansion | Sovereign reserve building & hard asset accumulation |
| Institutional Allocation | Equities, high-beta credit, consumer debt | Physical bullion, strategic energy, industrial metals |
| Consumer Sentiment | Robust expectations & high investment confidence | Depressed expectations & spending caution |
| Reserve Asset Priority | High paper yield & debt liquidity | Zero counterparty risk & asset tangibility |
How might this systemic migration toward hard commodity reserves play out across the macro landscape? Market participants are analyzing three main forward-looking scenarios:
Scenario A: The Structural Supercycle (High-Probability Outcome)
- The Dynamics: As consumer growth slows, sovereign entities accelerate strategic resource acquisition to protect against monetary debasement and geopolitical fragmentation.
- The Impact: Demand for physical collateral—ranging from precious metals to critical industrial elements like copper and lithium—creates a structural supply deficit. Wall Street analysts project that continued official-sector absorption could drive precious metals and scarce energy assets into prolonged multi-year bull cycles, redefining traditional portfolio construction. Merchant Gold Group
Scenario B: The Cyclical Rebound (Moderate-Probability Outcome)
- The Dynamics: A rapid easing of global monetary policy, combined with falling energy overheads, restores consumer purchasing power faster than expected.
- The Impact: As real wages recover and consumer spending rebounds, risk appetite surges back into traditional equities, consumer retail, and growth assets. Strategic commodity reserve accumulation slows to baseline levels, normalizing resource valuations.
Scenario C: The Stagflationary Squeeze (Low-to-Moderate Probability)
- The Dynamics: Geopolitical tensions cause renewed energy supply shocks while consumer confidence remains suppressed, creating a high-inflation, low-growth regime.
- The Impact: Institutional actors accelerate commodity hoarding to protect purchasing power, while consumer-facing sectors experience severe margin compression. Physical assets outperform financial assets across the board.
The shift toward hard commodity reserves is more than a hedge against near-term volatility—it represents a fundamental revaluation of monetary collateral in an era of consumer caution. When consumer-led GDP growth falters, institutional capital naturally gravitates toward assets with intrinsic value and zero counterparty liability.
Strategic Variables to Track:
- Consumer Confidence Sub-Indices: Monitor monthly trends in job security and investment sentiment to gauge when consumer demand might trough.
- Central Bank Purchasing Reports: Keep a close eye on World Gold Council reserve updates to see if official sector commodity buying maintains its historic pace.
- Real Yield Differentials: Measure real yields against physical metal performance to track whether investors remain willing to pay a positive carry cost to own hard assets.
- Supply-Side Deficits: Watch mine output vs. sovereign absorption rates across industrial and precious metals.
The structural economic playbook is changing. Whether hard commodity reserves remain the dominant institutional haven or serve as a bridge to the next recovery cycle depends on how long consumer headwinds persist.
Disclaimer: This article is strictly for informational, educational, and editorial purposes and does not constitute financial, investment, or legal advice. Speculative scenarios represent theoretical outcomes and market analysis, not guaranteed economic results.
To understand the broader economic context regarding global supply dynamics and long-term commodity projections, watch the World Bank Forecasts Global Commodity Prices Overview. This report unpacks how shifting global growth expectations and energy market trends are reshaping reserve strategies for developing and developed economies alike.